Maximize Your 2026 HSA Benefits: A 5-Step Guide to $3,850 Tax Savings
Anúncios
Maximizing your 2026 Health Savings Account (HSA) benefits through strategic contributions and informed utilization can lead to substantial tax savings, potentially up to $3,850, while securing your healthcare future.
Are you looking to secure your financial future while taking control of your healthcare costs? Understanding how to Maximize Your 2026 Health Savings Account (HSA) Benefits: A 5-Step Guide to $3,850 in Tax Savings is more crucial than ever. This guide will walk you through the essential steps to leverage this powerful financial tool, ensuring you make the most of its unique tax advantages and prepare for healthcare expenses both now and in retirement.
Anúncios
Understanding the Power of Your 2026 HSA
The Health Savings Account (HSA) remains one of the most advantageous financial instruments available for individuals enrolled in a high-deductible health plan (HDHP). For 2026, the contribution limits and benefits continue to make it an indispensable tool for healthcare savings and tax efficiency. It offers a triple tax advantage: tax-deductible contributions, tax-free growth, and tax-free withdrawals for qualified medical expenses.
Anúncios
Many Americans overlook the full potential of their HSA, often treating it merely as another savings account. However, with strategic planning, it can serve as a powerful long-term investment vehicle. The funds within an HSA can be invested, allowing your savings to grow over time, similar to a 401(k) or IRA, but with the added flexibility for healthcare costs.
Key HSA Features for 2026
Understanding the specific parameters for 2026 is the first step toward maximizing your benefits. These limits are crucial for planning your contributions effectively and avoiding any penalties.
- Contribution Limits: For 2026, the IRS typically adjusts contribution limits annually. These limits specify the maximum amount you can contribute to your HSA, which is a critical factor in determining your potential tax savings.
- Catch-Up Contributions: If you are aged 55 or older, you are eligible for additional catch-up contributions, allowing you to save even more towards your healthcare future. This provision is designed to help older individuals bolster their health savings as retirement approaches.
- HDHP Requirements: To be eligible for an HSA, you must be covered by an HDHP that meets specific deductible and out-of-pocket maximum thresholds. Verifying your plan’s compliance is essential for HSA eligibility.
The beauty of the HSA lies in its flexibility. Unlike a Flexible Spending Account (FSA), HSA funds roll over year after year, never expiring. This means any money you contribute and don’t use for current medical expenses can continue to grow tax-free, forming a substantial nest egg for future healthcare needs, including those in retirement. This long-term growth potential is a cornerstone of its appeal, distinguishing it from other short-term health savings options.
Step 1: Confirming Your 2026 HSA Eligibility and Contribution Limits
Before you can begin to fully capitalize on your HSA, the foundational step is to confirm your eligibility for 2026 and understand the updated contribution limits. Eligibility is tied directly to your health insurance plan and your individual tax status. Misunderstanding these criteria can lead to penalties and missed opportunities for significant tax advantages.
Eligibility typically requires enrollment in a high-deductible health plan (HDHP) that meets specific IRS criteria for deductibles and out-of-pocket maximums. It’s also important that you are not enrolled in Medicare, nor can you be claimed as a dependent on someone else’s tax return. These rules ensure that HSAs are utilized as intended for those with eligible health coverage.
Verifying Your HDHP Status
Your health insurance provider can confirm if your plan qualifies as an HDHP for HSA purposes. This involves checking both the minimum deductible and the maximum out-of-pocket limits for the upcoming year. For 2026, these figures are subject to annual adjustments by the IRS, so it’s imperative to consult the most current guidelines.
- Minimum Deductible: Ensure your plan’s deductible meets or exceeds the IRS-mandated minimum for HDHPs. This threshold ensures you bear a certain level of direct healthcare costs before your insurance fully kicks in.
- Maximum Out-of-Pocket: Your plan’s annual out-of-pocket maximum (including deductibles, co-payments, and co-insurance) must not exceed the IRS-defined limit. This protects you from catastrophic medical expenses.
- Other Health Coverage: Generally, you cannot have other health coverage that is not an HDHP, with some exceptions for specific types of coverage like dental, vision, or accident insurance.
Once you’ve confirmed your eligibility, the next critical piece of information is the 2026 contribution limits. These limits, typically announced by the IRS in the latter half of the preceding year, dictate the maximum amount you can contribute. For individuals, family plans, and those eligible for catch-up contributions, these figures are distinct. Understanding these limits enables you to plan your contributions strategically to hit the maximum, thereby maximizing your tax deductions and long-term savings potential. Failing to adhere to these limits can result in excess contribution penalties, negating some of the financial benefits you sought to achieve.
Step 2: Maximizing Your 2026 Contributions for Optimal Tax Savings
The cornerstone of maximizing your 2026 HSA benefits lies in strategically contributing the maximum allowable amount. This action directly translates into significant tax savings through pre-tax contributions and tax deductions. The power of an HSA is amplified when you consistently contribute the full amount, allowing your funds to grow untouched by taxes.
Many individuals contribute just enough to cover immediate medical expenses, missing out on the substantial long-term benefits. By aiming for the maximum contribution, you’re not just saving for healthcare; you’re investing in your future with a unique tax-advantaged vehicle. The tax savings of up to $3,850 mentioned in the title are often realized through a combination of federal tax deductions, potential state tax benefits, and avoiding FICA taxes if contributions are made through payroll deduction.
Strategies for Full Contribution
Reaching the maximum contribution limit for 2026 requires a proactive approach. It’s not always about having a large lump sum; consistent, planned contributions can be just as effective.
- Automate Contributions: Set up automatic payroll deductions or recurring transfers from your bank account to your HSA. This ‘set it and forget it’ method ensures you consistently contribute throughout the year without having to remember.
- Calendar Reminders: Mark your calendar for key dates, such as the tax filing deadline for the prior year, as you can often contribute to the previous year’s HSA up until this point. This provides an additional window to max out contributions.
- Budgeting for HSA: Integrate your HSA contributions into your monthly budget. Treat it as a non-negotiable expense, similar to rent or utilities, to prioritize this important savings vehicle.
For those aged 55 and over, remember to factor in the additional catch-up contribution. This extra amount can significantly boost your HSA balance, providing a more robust safety net for healthcare costs in retirement. Every dollar contributed up to the limit is a dollar that reduces your taxable income, potentially pushing you into a lower tax bracket and leading to greater overall savings. The compounding growth of these tax-free funds over years can result in a substantial sum, ready to cover medical expenses without dipping into your retirement savings. This long-term growth potential is a cornerstone of its appeal, distinguishing it from other short-term health savings options.
Step 3: Strategic Investment of HSA Funds
Once your HSA is funded, the next crucial step to maximize its long-term potential is to strategically invest your funds. An HSA is more than just a savings account; it’s a powerful investment vehicle that offers tax-free growth, a benefit typically reserved for retirement accounts. Letting your funds sit uninvested in a low-interest cash account means you’re missing out on a significant opportunity for wealth accumulation.
Many HSA providers offer a range of investment options, from mutual funds and exchange-traded funds (ETFs) to individual stocks. The key is to choose investments that align with your risk tolerance and financial goals, considering your time horizon until retirement. The longer your time horizon, the more aggressive you might choose to be with your investments, as you have more time to recover from market fluctuations.
Choosing Your Investment Path
Selecting the right investment strategy for your HSA involves understanding the options available and how they fit into your broader financial plan.
- Diversification: Spread your investments across different asset classes (stocks, bonds, mutual funds) to mitigate risk. A diversified portfolio is generally more resilient to market volatility.
- Low-Cost Index Funds/ETFs: These are often recommended for their low expense ratios and broad market exposure. They offer a simple yet effective way to grow your HSA funds.
- Risk Tolerance Assessment: Honestly assess your comfort level with investment risk. If you’re nearing retirement, a more conservative approach might be suitable, whereas younger individuals might opt for growth-oriented investments.
The power of tax-free growth cannot be overstated. Imagine your investments compounding over decades without being eroded by annual taxes on dividends or capital gains. This allows your HSA balance to grow significantly larger than it would in a taxable account. When it comes time to withdraw these funds for qualified medical expenses, those withdrawals are also tax-free, completing the triple tax advantage. This makes the HSA an unparalleled tool for both current and future healthcare funding, especially for those planning for substantial medical costs in retirement.
Step 4: Smart Utilization of HSA Funds for Qualified Medical Expenses
While contributing and investing are critical, knowing how to smartly utilize your HSA funds for qualified medical expenses is equally important. The tax-free withdrawal benefit is contingent upon using the funds for eligible expenses, as defined by the IRS. Understanding what constitutes a qualified medical expense ensures you maintain the tax-advantaged status of your withdrawals and avoid potential penalties.
The beauty of the HSA is its broad definition of qualified medical expenses. This includes everything from doctor’s visits, prescriptions, and dental care to vision care, chiropractic services, and even certain over-the-counter medications. It also extends to services like acupuncture, physical therapy, and even long-term care insurance premiums, providing comprehensive coverage for a wide array of health needs.
Maximizing Tax-Free Withdrawals
To truly maximize the tax-free withdrawal benefit, consider these strategies:
- Keep Detailed Records: Maintain meticulous records of all your medical expenses, even those you pay out-of-pocket. You can reimburse yourself for these expenses from your HSA at any point in the future, even years later, as long as the expense was incurred after your HSA was established.
- Delay Reimbursement: If you can afford to pay for current medical expenses out-of-pocket, consider doing so and letting your HSA funds continue to grow tax-free. You can then reimburse yourself for these accumulated expenses later in life, potentially during retirement, when your HSA balance has grown significantly.
- Understand Eligible Expenses: Familiarize yourself with IRS Publication 502, which details what constitutes a qualified medical expense. This knowledge prevents accidental non-qualified withdrawals that could incur taxes and penalties.
The ability to pay for current medical expenses with after-tax dollars and then reimburse yourself years down the line, tax-free, is a powerful strategy. This allows your invested HSA funds more time to grow, maximizing the compound interest effect. Essentially, your HSA can become a pseudo-retirement account specifically for healthcare costs, allowing your other retirement savings to be used for general living expenses. This strategic approach to withdrawals is a key component of truly maximizing your 2026 HSA benefits, turning it into a robust financial asset.
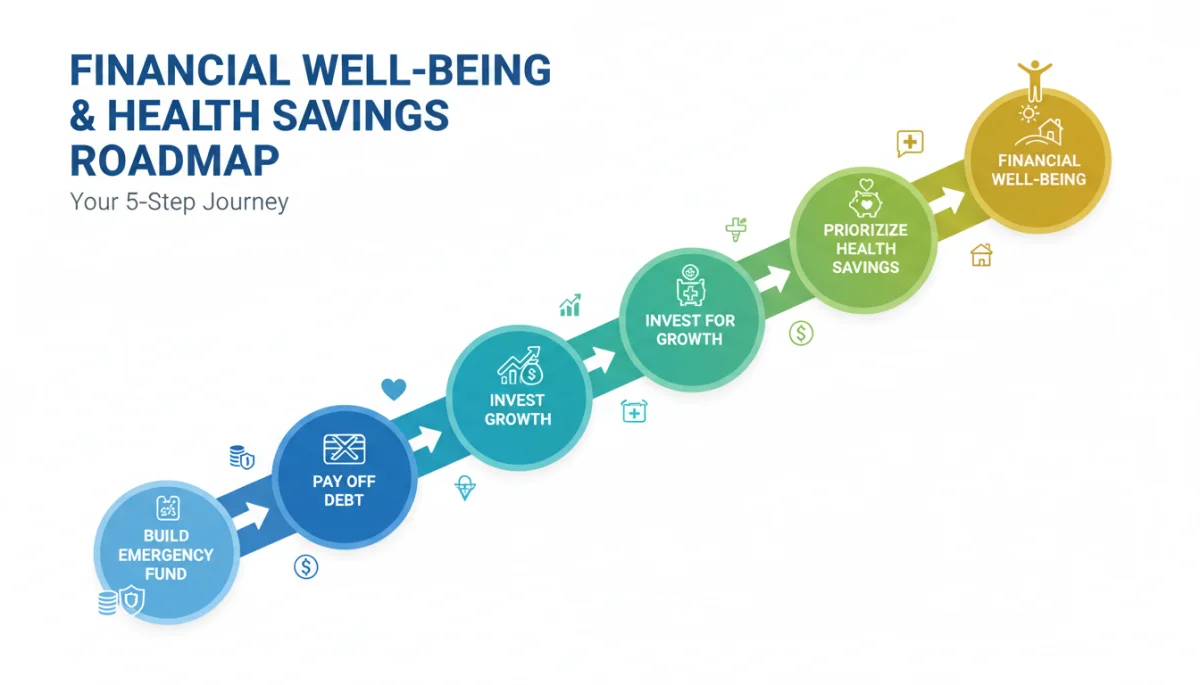
Step 5: Leveraging HSA as a Retirement Healthcare Fund
The ultimate strategy for maximizing your 2026 HSA benefits extends beyond immediate healthcare needs; it involves leveraging it as a dedicated retirement healthcare fund. This long-term perspective transforms your HSA from a mere savings account into a powerful tool for financial security in your golden years. Many underestimate the significant healthcare costs retirees face, and an HSA can be a crucial buffer against these expenses.
Once you reach age 65, your HSA funds can be withdrawn for any purpose without penalty, though non-qualified withdrawals will be subject to ordinary income tax. However, if used for qualified medical expenses, withdrawals remain tax-free. This dual flexibility makes the HSA a unique and valuable asset in retirement planning, offering both healthcare funding and a supplementary income source if needed.
Long-Term HSA Strategies for Retirement
Planning for retirement with your HSA requires a forward-thinking approach to contributions, investments, and utilization.
- Maximize Contributions Annually: Consistently contribute the maximum allowable amount each year, including catch-up contributions once eligible. The more you save early on, the more your investments can grow.
- Aggressive Investment Strategy (Early On): In your younger years, consider a more aggressive investment strategy within your HSA to maximize growth potential. As you approach retirement, gradually shift to a more conservative allocation to protect your capital.
- Save Receipts for Future Reimbursement: As mentioned, saving receipts for out-of-pocket medical expenses allows you to reimburse yourself tax-free from your HSA at any point in the future. This strategy effectively turns your HSA into a tax-free reimbursement account for past medical costs, allowing your funds to grow longer.
Consider the scenario where you accumulate hundreds of thousands of dollars in your HSA by retirement age. This substantial fund can cover Medicare premiums, deductibles, co-pays, and even long-term care expenses, significantly reducing the burden on your other retirement savings. By treating your HSA as a long-term investment vehicle from the outset, you’re not just saving for healthcare; you’re building a robust financial safety net that offers unparalleled tax advantages and peace of mind for your retirement years. The ability to use these funds tax-free for medical expenses in retirement provides a critical advantage, making the HSA an indispensable component of comprehensive financial planning.
Navigating Common HSA Misconceptions
Despite the clear advantages, many individuals harbor misconceptions about HSAs that prevent them from fully utilizing this powerful financial tool. Dispelling these myths is crucial for maximizing your 2026 HSA benefits. One common misconception is that HSA funds are ‘use it or lose it,’ similar to Flexible Spending Accounts (FSAs). This is incorrect; HSA funds roll over indefinitely, making them a long-term savings vehicle.
Another misunderstanding is that HSAs are only beneficial for those with significant current medical expenses. While they certainly help with immediate costs, their true power lies in their investment potential and ability to cover future, often unpredictable, healthcare needs, especially in retirement. Many also believe that once they enroll in Medicare, they can no longer use their HSA. While new contributions are prohibited, you can continue to use your existing HSA funds tax-free for qualified medical expenses, including Medicare premiums.
Clarifying HSA Realities
Understanding the true nature of HSAs can unlock their full potential for your financial planning.
- Not Just for the Healthy: While those with few medical expenses can benefit greatly from the investment growth, HSAs are also invaluable for those with chronic conditions, providing a tax-advantaged way to pay for ongoing care.
- Investment Flexibility: Many HSA providers offer a wide range of investment options. You are not limited to a simple savings account; you can choose investments that align with your financial goals and risk tolerance.
- Portable Across Jobs: Your HSA is yours, even if you change employers or health plans. The funds remain yours, allowing for continuous growth and utilization regardless of your employment status.
Furthermore, some believe that withdrawing funds for non-medical expenses before age 65 is always subject to a 20% penalty. While this is true, it’s important to remember that after age 65, non-qualified withdrawals are only subject to ordinary income tax, similar to a traditional IRA. This flexibility in retirement adds another layer of appeal, offering a potential source of income if healthcare costs are lower than anticipated. By moving past these common misconceptions, you can better appreciate the comprehensive benefits an HSA offers and integrate it more effectively into your overall financial strategy for 2026 and beyond.
The Broader Impact of Your HSA on Financial Health
Beyond the immediate tax savings and healthcare funding, your HSA plays a significant role in your overall financial health and long-term planning. It acts as a powerful complement to your other retirement accounts, providing a dedicated, tax-advantaged fund specifically for healthcare costs, which are often a major financial concern in retirement. By effectively managing your HSA, you free up your 401(k) and IRA funds for general living expenses, travel, or other retirement goals.
The proactive management of your HSA also fosters a greater sense of financial literacy and control over your healthcare spending. It encourages you to be more mindful of medical costs, seek out transparent pricing, and make informed decisions about your health. This engagement can lead to better health outcomes and more efficient use of your healthcare dollars, further enhancing your financial well-being.
Integrating HSA into Your Financial Plan
To maximize the broader impact of your HSA, consider these integration strategies:
- Emergency Fund Supplement: While not its primary purpose, your HSA can serve as a backup emergency fund for unexpected medical costs, providing a safety net that is also tax-advantaged.
- Estate Planning: In the event of your passing, your HSA can be transferred to a spouse tax-free, maintaining its tax-advantaged status. If transferred to a non-spouse beneficiary, it loses its HSA status but can still be a valuable asset.
- Long-Term Care Planning: HSA funds can be used to pay for qualified long-term care services and long-term care insurance premiums, addressing one of the most significant potential expenses in retirement.
The strategic use of your HSA can significantly reduce your financial stress related to healthcare, allowing you to focus on other aspects of your financial future. It offers peace of mind, knowing that a dedicated, tax-free fund is growing to meet your medical needs. This holistic approach to financial planning, with the HSA at its core for healthcare, ensures a more robust and secure future, making it an indispensable tool for every eligible American to consider for 2026 and beyond. Embracing these strategies can truly transform your financial outlook, providing both immediate tax advantages and long-term security.
| Key Aspect | Brief Description |
|---|---|
| Eligibility & Limits | Must have an HDHP meeting IRS criteria; adhere to 2026 contribution limits, including catch-up for age 55+. |
| Maximize Contributions | Contribute the maximum allowable amount annually for significant tax deductions and long-term savings. |
| Invest Funds Strategically | Invest HSA funds in diversified, low-cost options for tax-free growth, aligning with risk tolerance. |
| Smart Utilization | Pay out-of-pocket for current expenses, save receipts, and reimburse later to maximize tax-free growth. |
Frequently Asked Questions About 2026 HSA Benefits
The main tax advantages of an HSA in 2026 include triple tax benefits: tax-deductible contributions, tax-free growth on investments, and tax-free withdrawals for qualified medical expenses. This makes it a highly efficient savings and investment vehicle for healthcare.
No, once you enroll in Medicare, you are no longer eligible to make new contributions to an HSA. However, you can continue to use any existing HSA funds tax-free for qualified medical expenses, including Medicare premiums, even after enrolling.
Your HSA is portable, meaning the funds belong to you, not your employer. If you change jobs, your HSA goes with you. You can continue to use the funds for qualified medical expenses and can transfer them to another HSA provider if you wish.
Yes, many over-the-counter medications and products are considered qualified medical expenses for HSA withdrawals. This includes items like pain relievers, cold medicines, bandages, and even feminine hygiene products, expanding the utility of your HSA funds.
By consistently maximizing contributions and investing your HSA funds, you can accumulate a substantial balance. After age 65, withdrawals for qualified medical expenses remain tax-free, and even non-qualified withdrawals are only subject to ordinary income tax, similar to a traditional IRA, offering retirement income flexibility.
Conclusion
Maximizing your 2026 Health Savings Account benefits is a strategic financial move that offers unparalleled tax advantages and long-term financial security. By diligently confirming your eligibility, consistently contributing the maximum allowable amounts, strategically investing your funds, and smartly utilizing them for qualified medical expenses, you can unlock significant tax savings and build a robust financial safety net for your healthcare needs, both now and in retirement. The HSA is more than just a savings account; it’s a powerful investment tool that, when used effectively, can profoundly impact your overall financial well-being and provide peace of mind for the future.